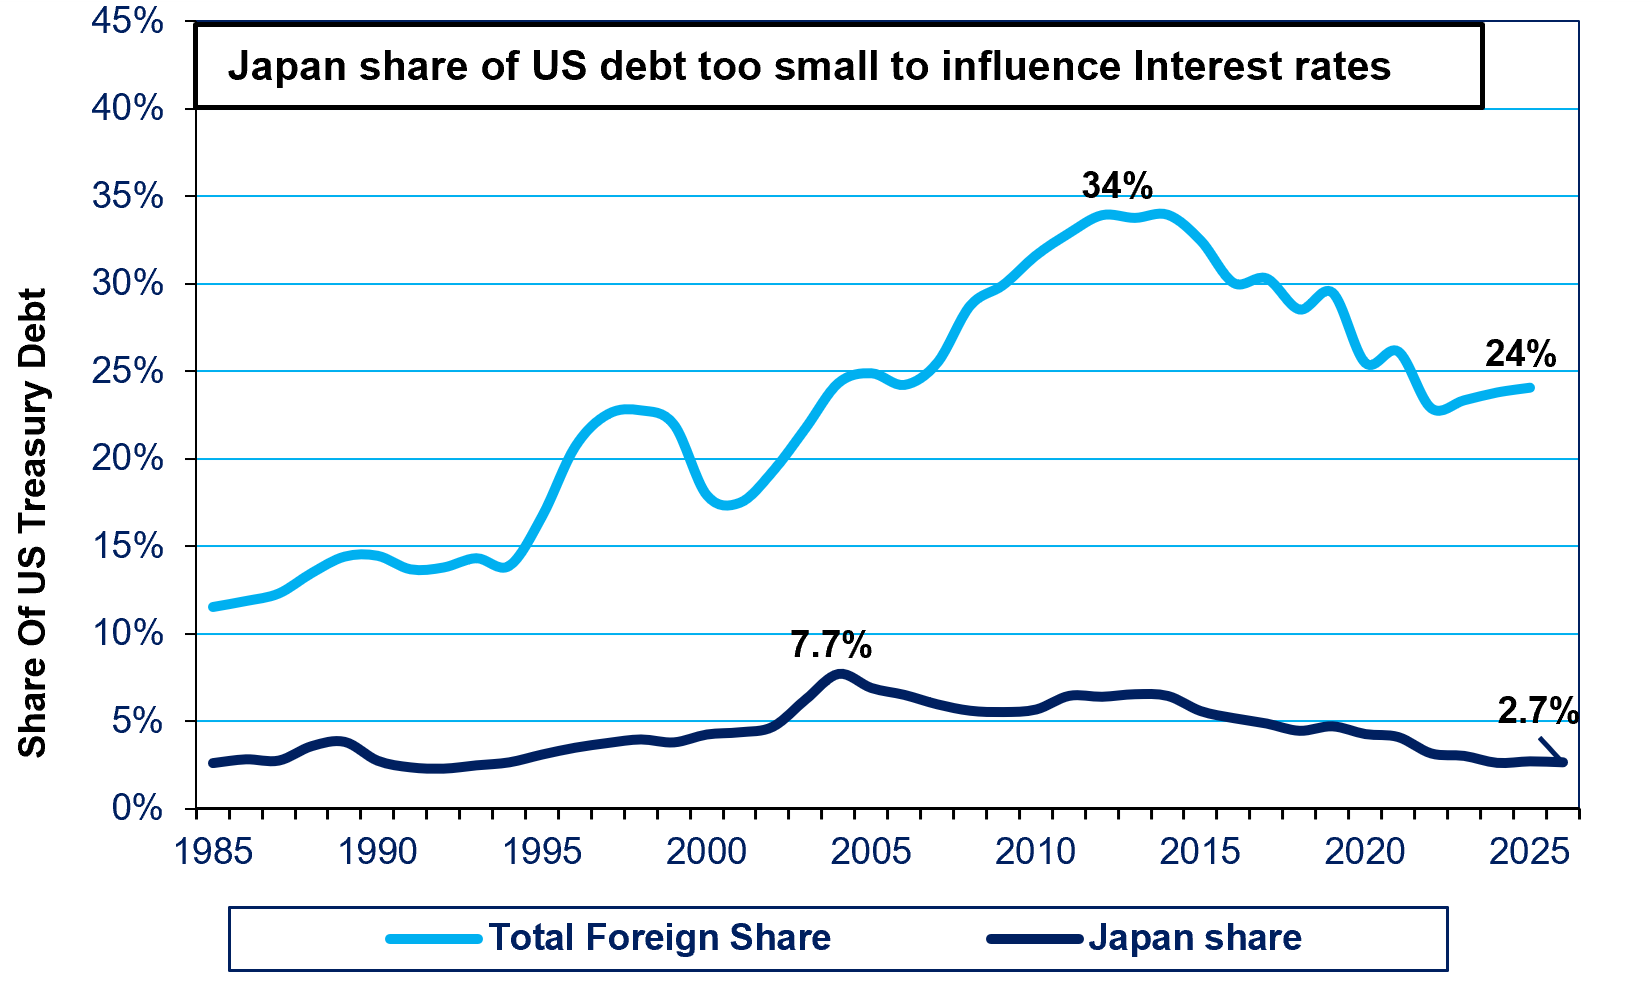
Source: https://fred.stlouisfed.org/series/GFDEBTN, https://fred.stlouisfed.org/series/FDHBFIN# , https://fred.stlouisfed.org/series/FORLTTREASPOS42609
Somehow, it’s become the consensus view that the US intervened to support the yen in order to prevent a spike in American interest rates. To my mind, this view is so much at variance with both the evidence and economic logic that it’s hard for me to fathom how it became so widely adopted, even among people whose views I generally respect. It’s also become consensus that if the Bank of Japan (BOJ) raised the overnight rate, the yen would appreciate. That, too, is belied by the data. I discussed the second issue in yesterday’s memo for paid subscribers and will add some additional evidence here.
Yen Share of US Debt Too Small; Plus Yen Holdings Have Declined 20% Since 2020 With No Impact
All of the articles and investment newsletters arguing that US Treasury Secretary Scott Bessent acted due to fears about US interest rates cite the fact that Japan (both private investors and the government) is the biggest foreign holder of US Treasury debt. True enough. What they omit is that, even so, Japan’s holdings now amount to only 2.7% of all Treasury debt. Moreover, this is down from a peak of 7.7% two decades ago (see chart at the top).
These commentaries also note that Japanese investors hold more than $1 trillion in Treasury bonds, which may seem like an impressive figure. But total outstanding Treasury bonds now amount to almost $40 trillion (see chart below). With that knowledge, $1 trillion becomes a lot less impressive.
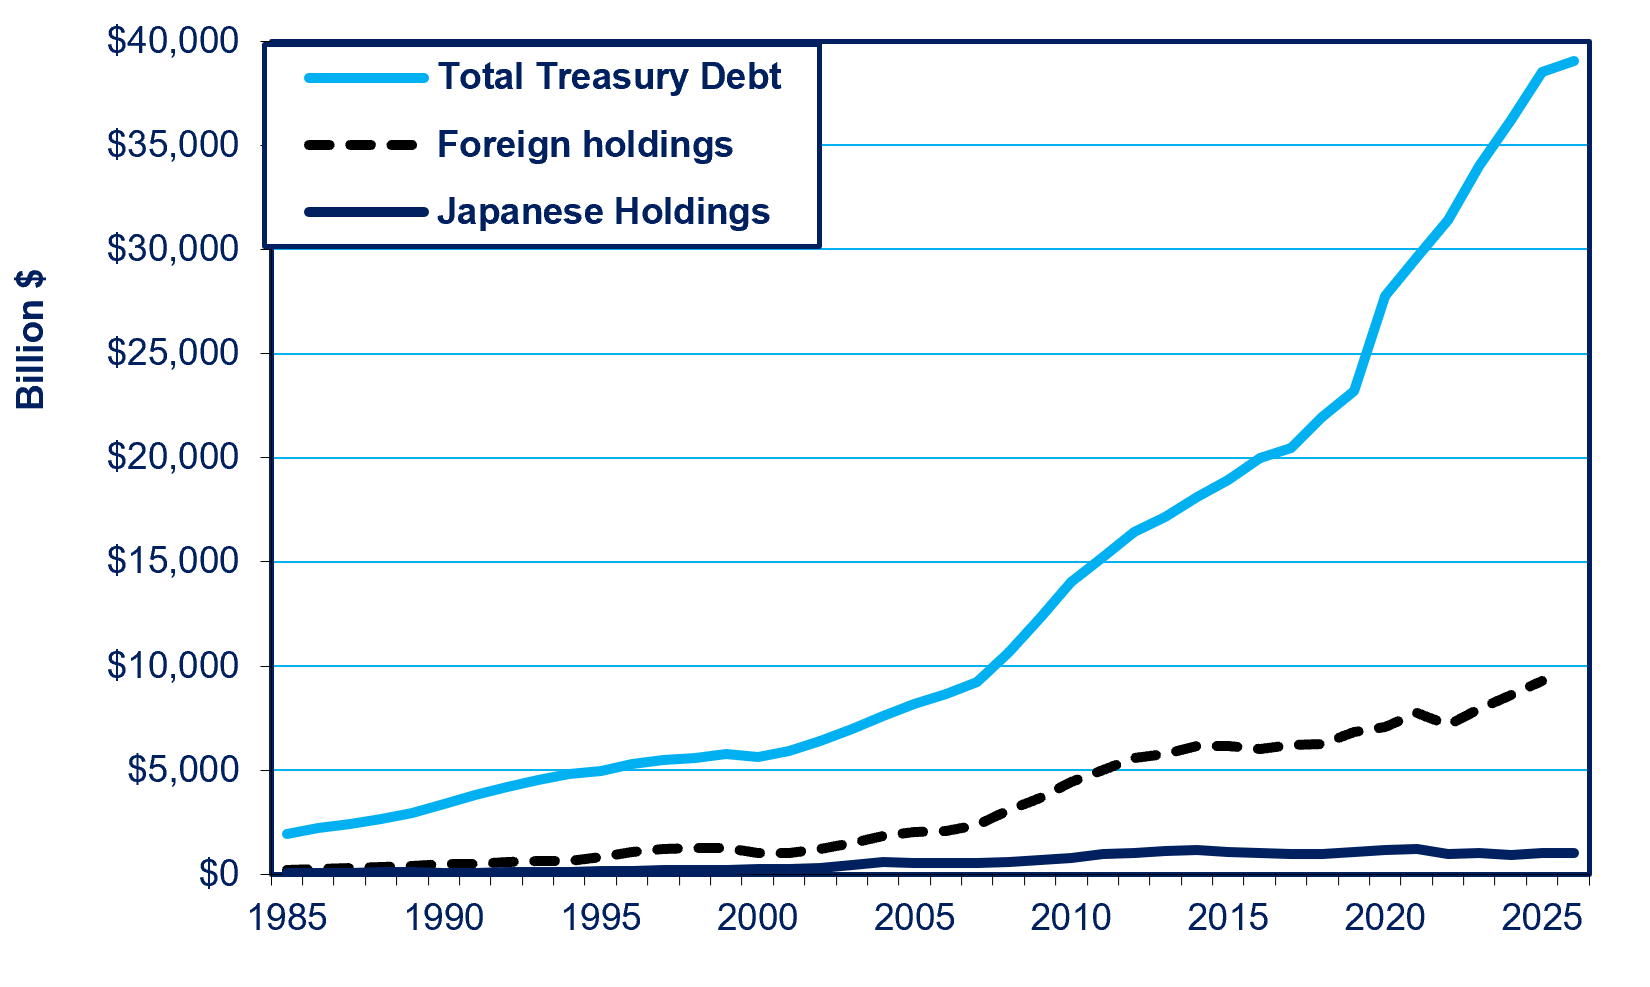
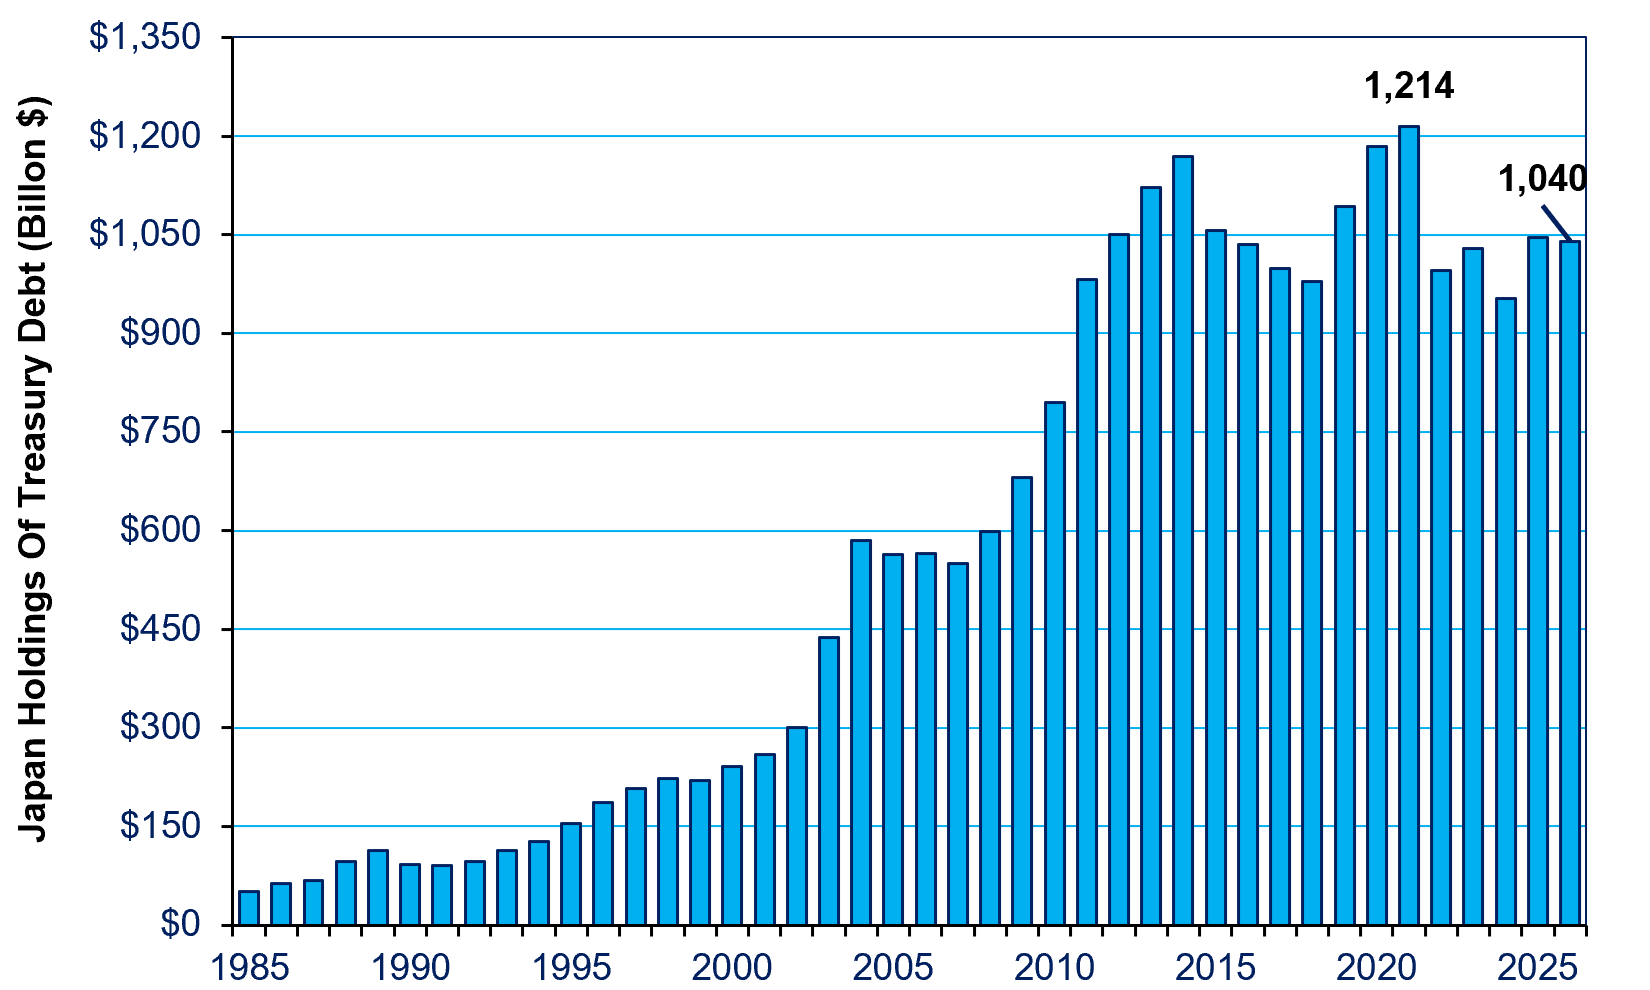
The bottom line is that Japan’s holdings are simply too small to have much impact even if Japanese investors drew down their holdings. We know this is true because Japanese investors have already drawn down their holdings by 16% since 2021, with no noticeable impact on US interest rates (see chart below).
If Bessent Is Worried, Why Is He Urging Japan to Hike Interest Rates?
A related myth was put forth earlier in the year: that rising interest rates in Japan were bound to trigger a spike in US interest rates. The logic was the following: because the gap in interest rates between the US and Japan was so high for so long, lots of investors spent years borrowing money at ultra-low rates in Japan in order to invest at higher rates in the US. This was called the “carry trade,” and, supposedly, it kept US rates from rising. Once the gap in interest rates narrowed, it was argued, then the money would stop flowing in from Japan, and US rates would spike. I refuted that contention back in a post in February on the same grounds as today: that Japan’s share of American public and private debt was too small to make a significant difference, and that the carry trade had already shrunk a great deal.
But that raises a curious conundrum about the commentators’ logic regarding Bessent’s motivations. The Trump administration is determined to keep US rates down. Trump is still trying to fire a member of the Federal Reserve Board based on false allegations, in order to create a majority in favor of low rates. If Bessent were worried that higher rates in Japan would lead to higher rates in the US, why, then, has he repeatedly urged the Takaichi administration and the BOJ to raise interest rates, a tack he began almost as soon as the Takaichi came into office on a program of keeping rates low? I wrote about this issue in a memo this May. Bessent raised the issue again just after the latest yen intervention, albeit obliquely: saying that the intervention won’t work unless followed by macroeconomic policy moves (read: higher interest rates).
Here’s my view of what’s driving Bessent. Trump wants a weak dollar and believes that other countries are cheating the US by keeping their currencies cheap. That, Trump argues, is why the US runs a trade deficit. Bessent believes—falsely in my view—that Tokyo could strengthen the yen by raising interest rates, including the overnight policy rate of the BOJ. But why would he push this so strongly if he believed that higher rates in Japan would raise rates in the US? On the contrary, I believe Bessent believes he can fulfill both of Trump’s priorities—making Asian currencies stronger and keeping US rates low—via the same instrument: raising Japanese overnight rates.
Higher Rates In Japan Don’t Raise Rates in the US
The fact of the matter is that, because Japanese holdings of US debt are so small, higher rates in Japan do not lead to higher rates in the US. On the contrary, despite a steady rise in Japanese 10-year government bonds (JGBs) since January 2024, the interest rate on ten-year T-bonds has traded within a very narrow range during that period: mostly between 4.0% and 4.5% (see the chart below).
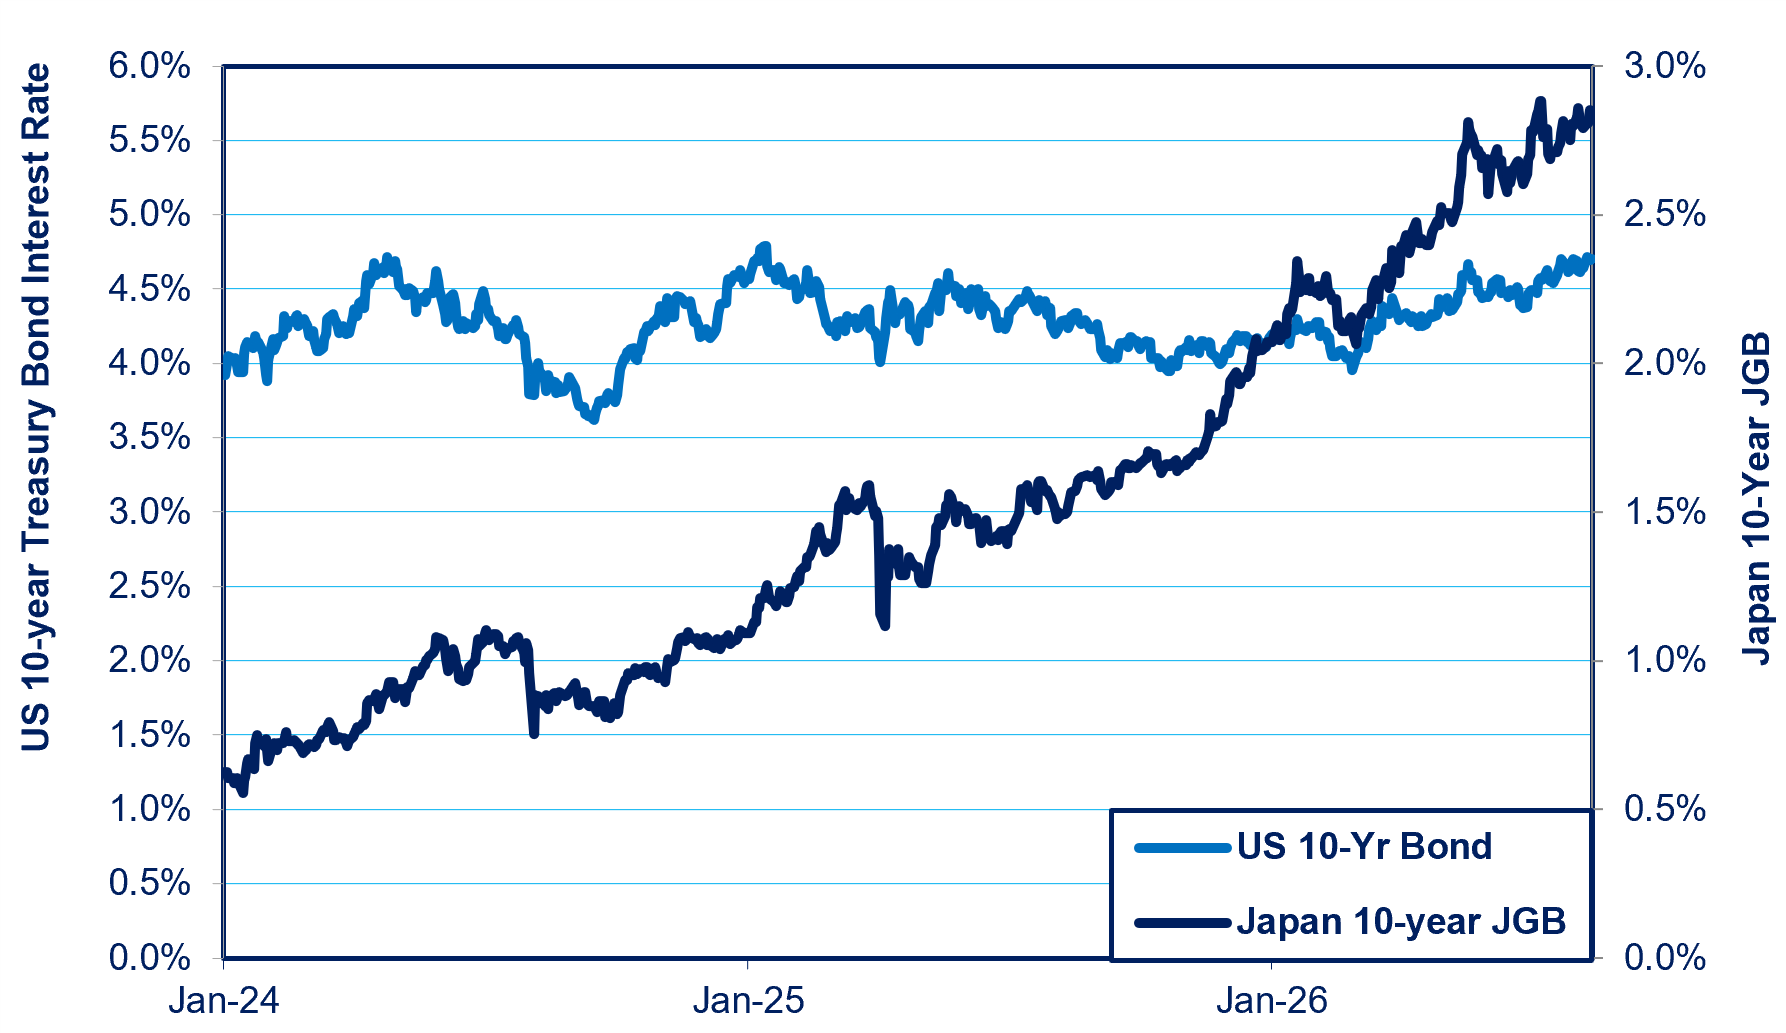
Source: WSJ
For further details on why neither a hike in Japanese rates nor a decline in Japanese holdings of US debt will make a significant impact on US interest rates, see this past blog posting and this one.
Higher Interest Rates Have Not Boosted Yen in Last Couple Years
The consensus view is that if only the BOJ raised interest rates, the yen would strengthen. I disagree. First, let’s note that due to the rise in Japanese long-term rates, the gap between US and Japanese rates has more than halved (see chart below).
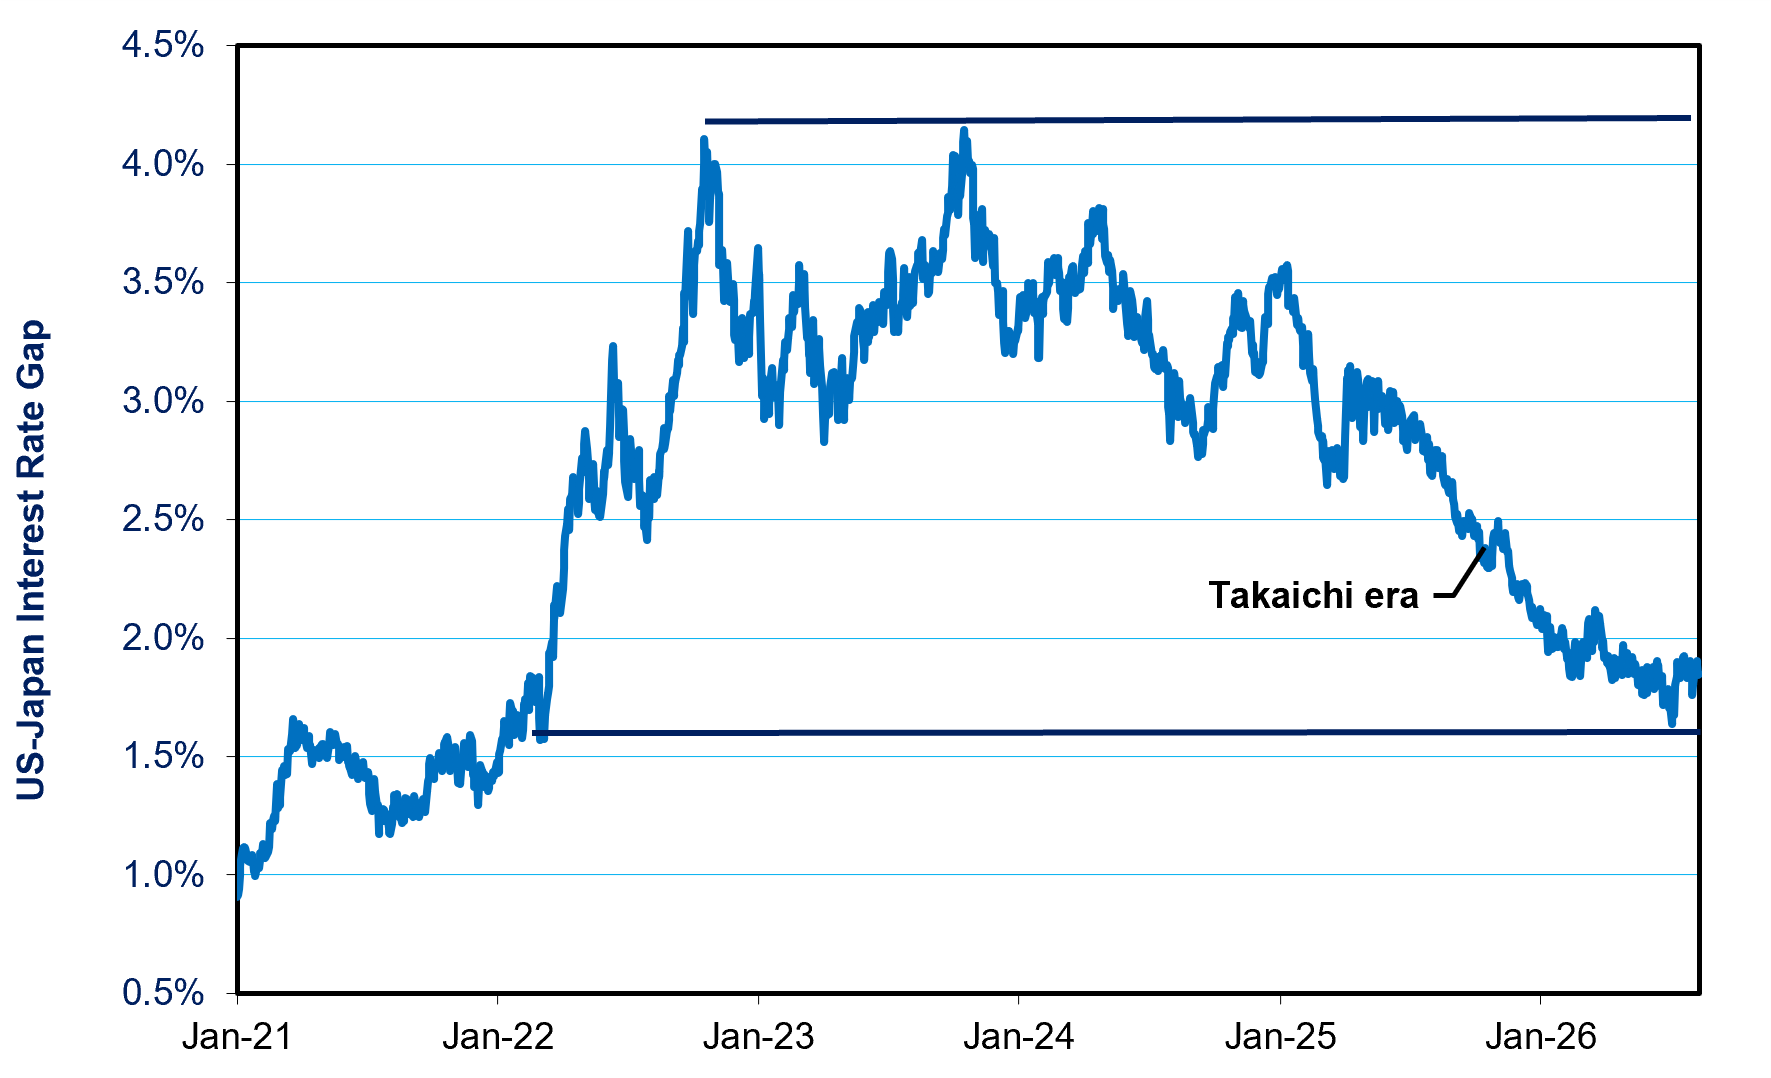
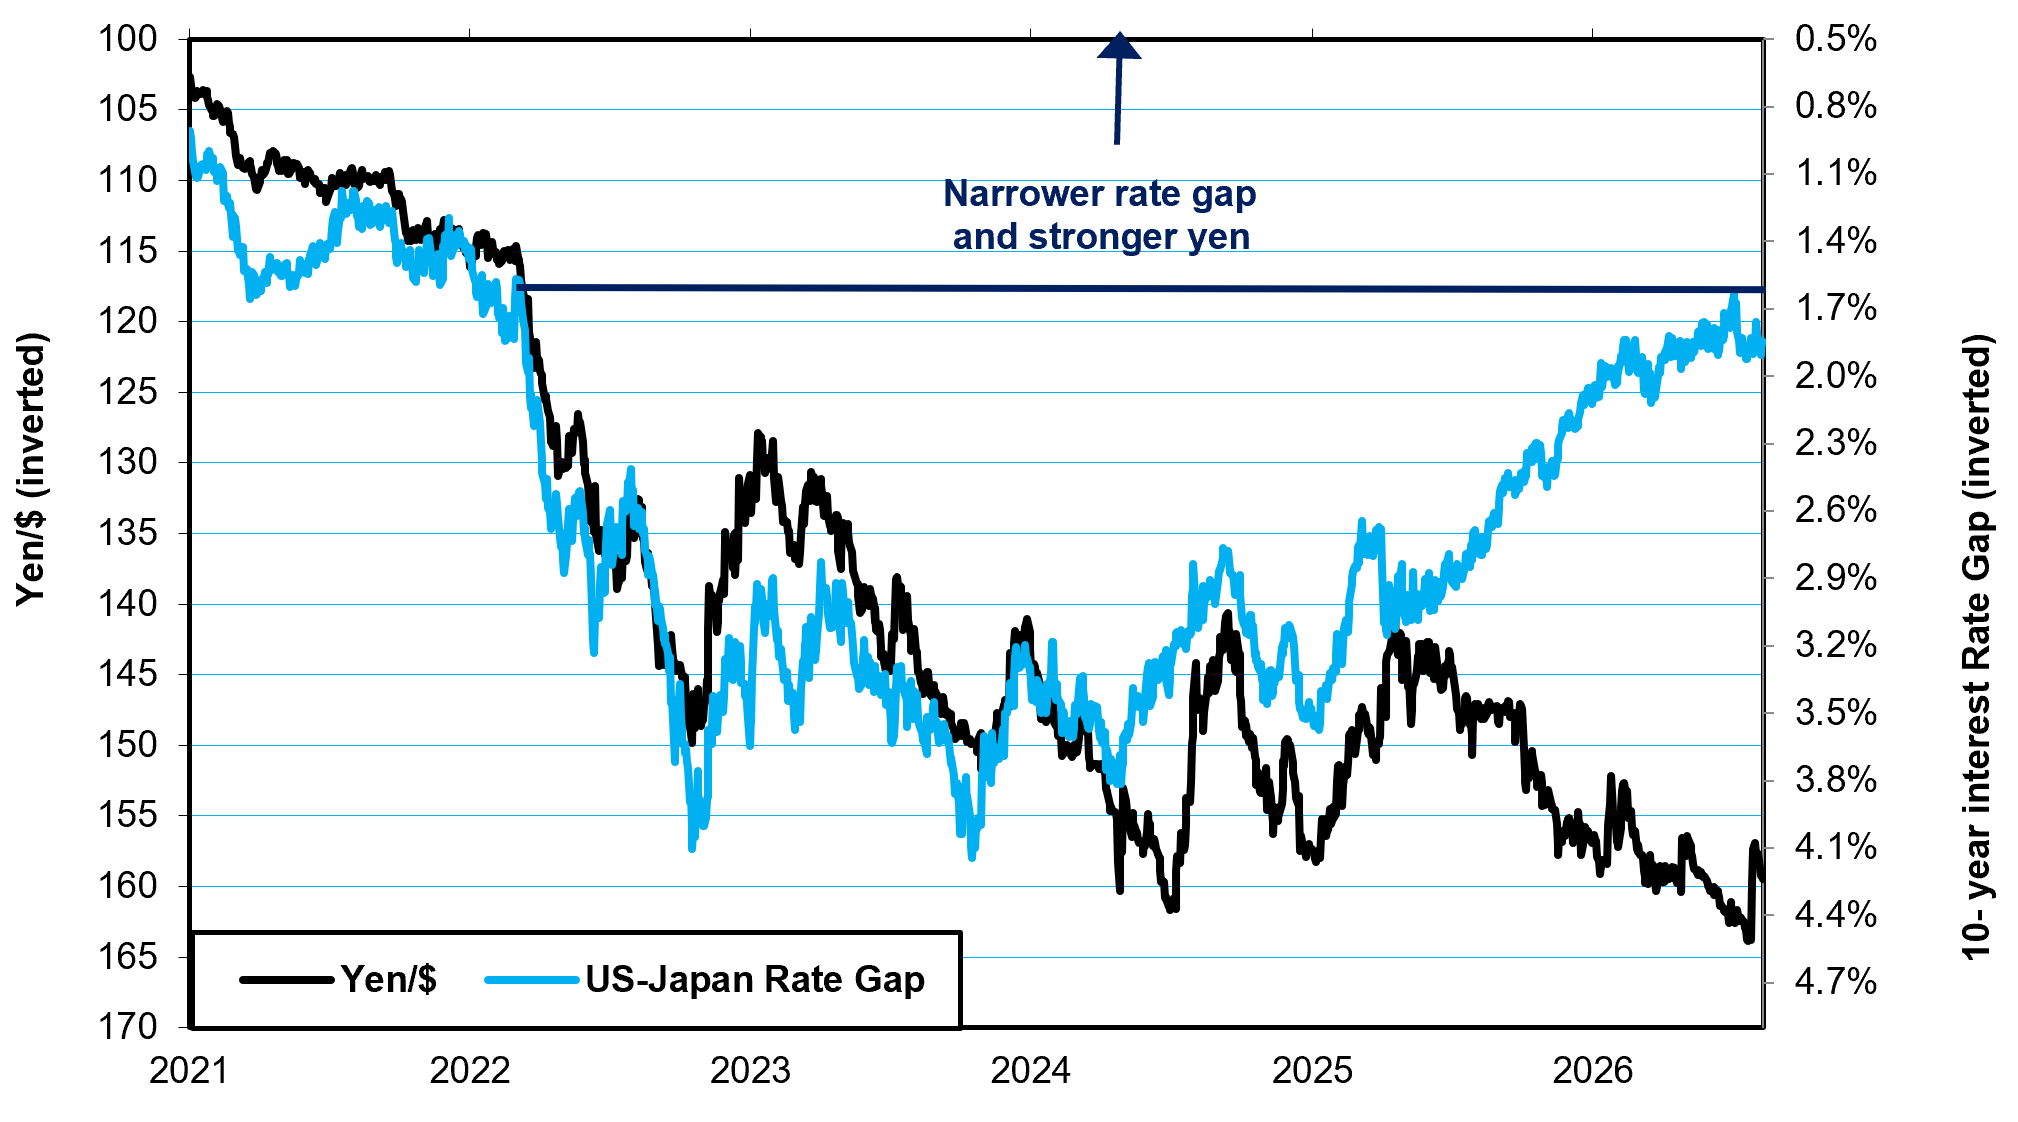
And yes, in the past, a narrower rate gap usually led to a stronger yen, but that has not been true ever since early 2025. On the contrary, even as the rate gap narrowed, the yen got weaker for reasons I discussed in yesterday’s post (see the chart below).
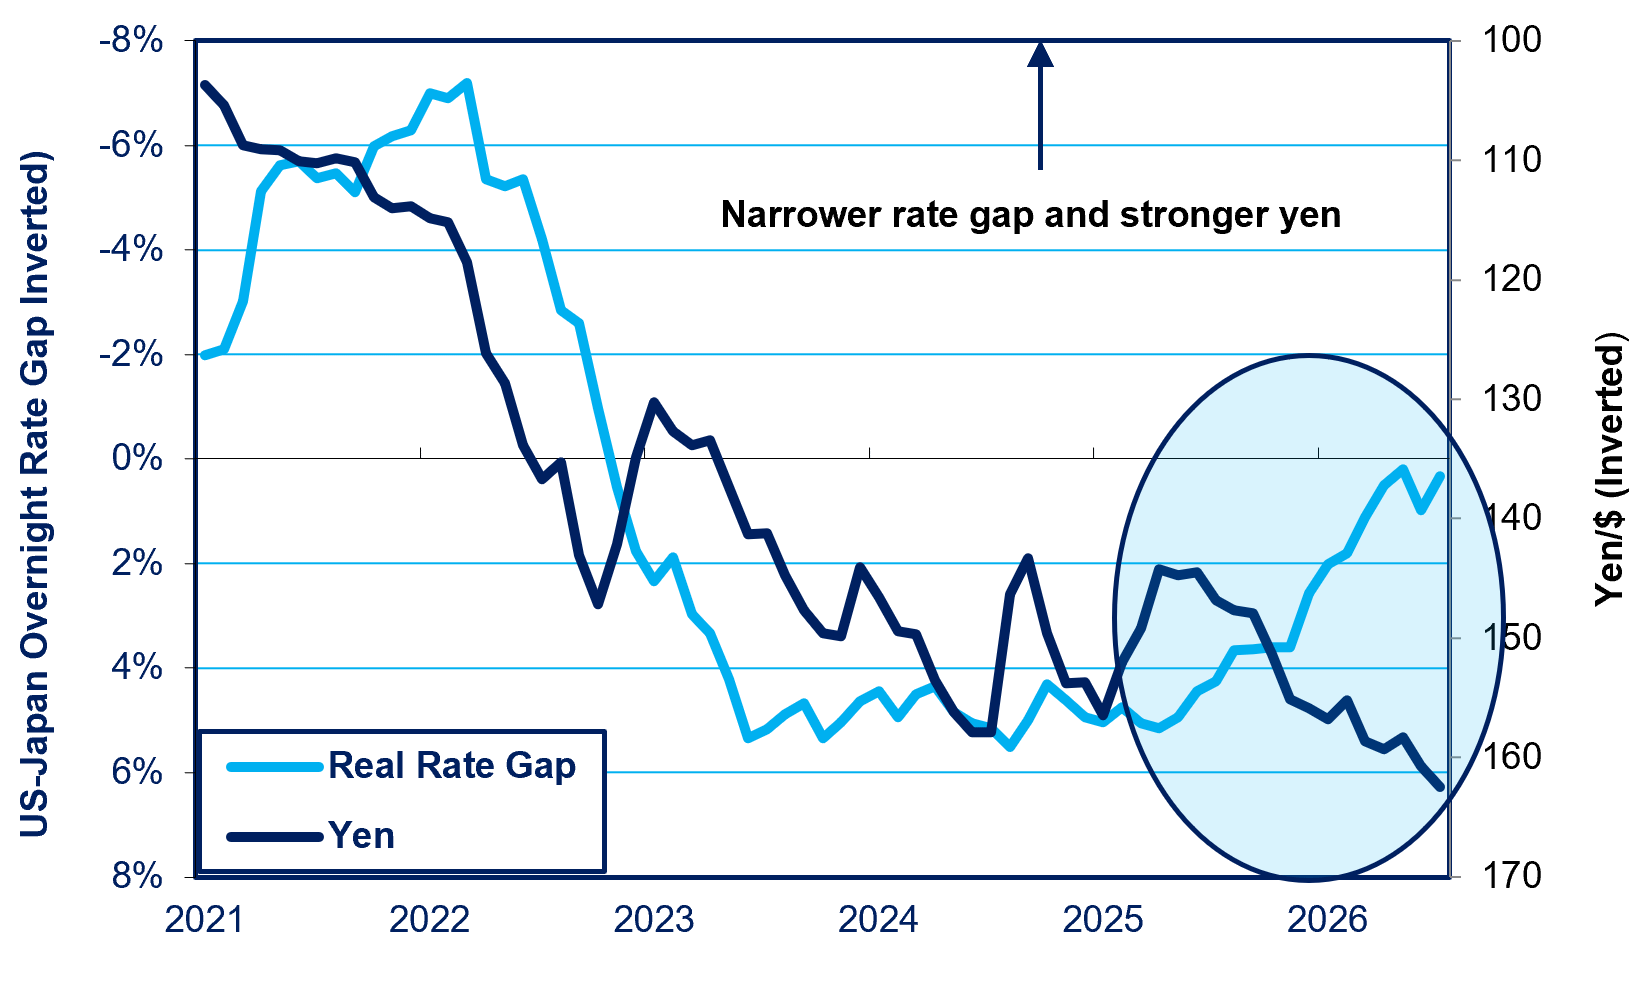
Instead of comparing the rate gap on ten-year government bonds, some commentators say we need to compare the real (i.e., after inflation) gap between the Japanese and American overnight central bank rates. I do that in the chart below. The result is similar to what we saw regarding the ten-year bonds. There was a correlation between a narrower rate gap and a stronger yen during 2021-2023. Beginning in 2024, the yen gyrated even as the rate gap barely moved. And, since late 2025, the yen has weakened even though the BOJ has raised the overnight rate. Whatever impact a narrower rate gap may have, it is being overwhelmed by other factors. So, why should anyone believe that another couple hikes by the BOJ would automatically boost the yen by a meaningful amount, if at all?
Support the Blog
Paid subscribers will be eligible for my new memos, an addition to these regular posts. Beyond that, if you feel you’ve gained insight from this blog, ever restacked it, if you ever subscribed to my previous publication, The Oriental Economist Report, and certainly, if you or your firm have gained insights that helped guide your investments, please support the blog with a subscription or by “buying me a cup of coffee.” You can buy a cup or two on a one-time basis, or once a year, or once a month.


I agree regarding the motivations of Bessent. But in his defense this was the playbook in 1985 post Plaza and it worked. Probably too well as we subsequently experienced. I get it regarding PPP. Millions of visitors are experiencing the joys of dirt cheap Japan. Even Bloomberg jumped on board this week with a silly katsu curry index. This week 2000 grocery items are set to increase by 15%. Robin Brooks frequently posts an effective policy would be for the BOJ to stop buying JGBs and let rates find the market (at risk of fiscal crisis). Perhaps an effective strategy to keep JPY from blowing thru 170 is to throw everything at it while working on the economy and stopping PRC/Taiwan from taking all the value in almost every important market. Oh, and by the way, once food consumption tax goes from 8% to 1% it’s not going back to 8%, no matter promises made now.
I think the 2.7% figure is useful, but it may understate the relevant transmission mechanism. The question is not whether Japan owns enough Treasuries to mechanically determine U.S. yields. It is whether a disorderly yen move changes the marginal allocation of global capital.
Exchange rates, term premia and Treasury yields are set at the margin, not by proportional ownership of the outstanding stock. A sharp yen depreciation can trigger carry-trade deleveraging, FX-hedging adjustments, repatriation incentives and correlated portfolio rebalancing across Japanese banks, insurers and global leveraged investors. Those flows can affect Treasury liquidity and term premia even if Japan’s total Treasury holdings are only a small percentage of the market.
That said, I agree with the broader conclusion that protecting U.S. yields was probably not the primary objective. The stronger explanation is that Washington viewed the yen move as potentially disorderly, with spillovers across JGBs, Asian FX and global risk markets. In that framework, Treasury-market stability is one transmission channel of concern, rather than the underlying reason for intervention.